Liquidity Cascades & the Evolution of Financial Markets
SEP 23, 2022 • 24 Min Read
This paper is a logical continuation and practical application of many concepts that were discussed in the report “Reflexivity & the Fall of the Efficient Market Hypothesis.” These concepts include reflexivity, feedback loops (both positive and negative), incentives, and many more. Please give this paper a read if you have not already had the chance to do so! This topic was heavily inspired by a paper written several years ago by Corey Hoffstein of Newfound Research, titled, “Liquidity Cascades – The Coordinated Risk of Uncoordinated Market Participants.” Several core concepts are paraphrased in this report for simplicity.
Financial Markets Are Always Evolving
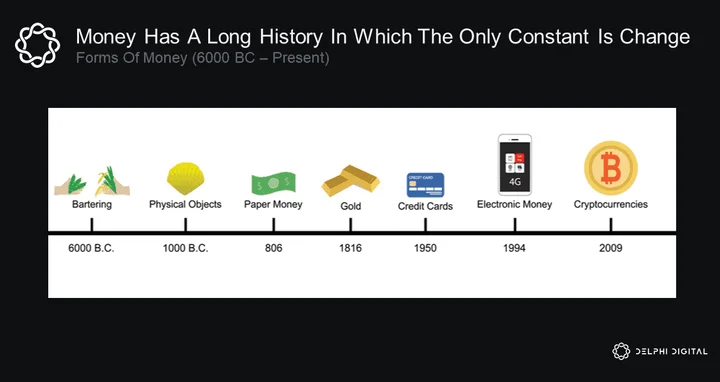
Markets have continually changed throughout history. From the famous accounts of Nathan Rothschild utilizing his vast wealth and communications channels to ascertain the result of the Battle of Waterloo before most, allowing him to make tremendous profits in Gilt markets, to the ticker tape readers of the early 1900s, and to the now infamous rise of high-frequency trading, one thing has remained consistent – the ever-evolving nature of financial markets and the strategies utilized within them. As markets and the dynamics at play continue to evolve and change with advances in technology, many of the most prominent frameworks for thinking about these markets over the previous decades are becoming redundant.
Perhaps one of the most important changes over the last two decades has been the frequency in which sudden drawdowns (also known as liquidity cascades) have impacted financial markets. Financial markets have always had risks of sudden sell-offs. Many have theorized that as markets get more mature and greater in size, they will tend to exhibit lower volatility profiles. This has not been the case, however.
We have seen an increase in the frequency of liquidity cascades occurring within financial markets – a direct contradiction to prevailing theory. Even more interesting is that even while experiencing more frequent liquidity cascades, equity markets have also benefited from one of the strongest bull markets in history. So how do we make sense of this?
Many people attribute this behavior to three main factors:
-
Increased use of accommodative monetary policy
-
The rise and prominence of passive investing and its implications
-
Fickle liquidity in the face of increasing margin requirements
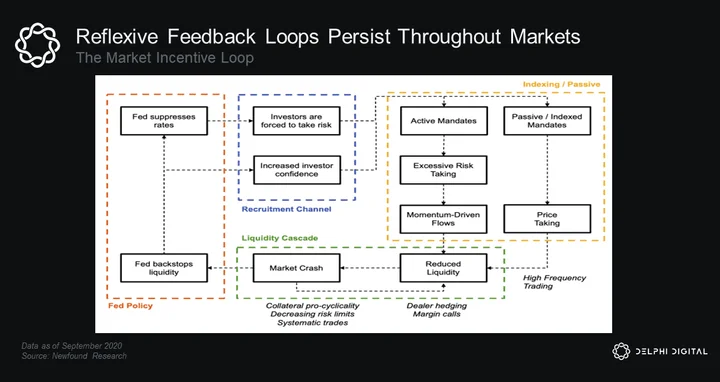
Interestingly, the common denominator behind all of these risk factors is liquidity. These three factors come together to form the “Market Incentive Loop.” The Market Incentive Loop is a real-world application of the reflexive feedback loops discussed in our Reflexivity Report.
Risk Factor 1: Accommodative Monetary Policy
The 2008 GFC gave birth to a new era of experimental monetary policy decisions in the form of QE and many of its successive programs. While these programs were initially aimed at stabilizing financial markets – both domestic and international – it was also the point of no return for many central banks. It was at this precise moment that central banks, led by the Federal Reserve, went from reactive referees to the most active, dominant market participants.
The actions taken by central banks to avoid a global financial meltdown had two major knock-on effects within financial markets. The first was a reduction in short-term interest rates. This provided investors with more incentives to take incremental risk. Complementary programs, such as QE, also provided investors with the second knock-on effect – renewed confidence, and thus the ability to take on additional risk.
Federal Reserve Governor Jeremy Stein discusses this exact dynamic in a speech from 2013, stating, “Thus, according to this theory, an easing of monetary policy affects long-term real rates not via the usual expectations channel, but rather via what might be termed a “recruitment” channel — by causing an outward shift in the demand curve of yield-oriented investors, thereby inducing these investors to take on more interest rate risk and to push down term premiums.”
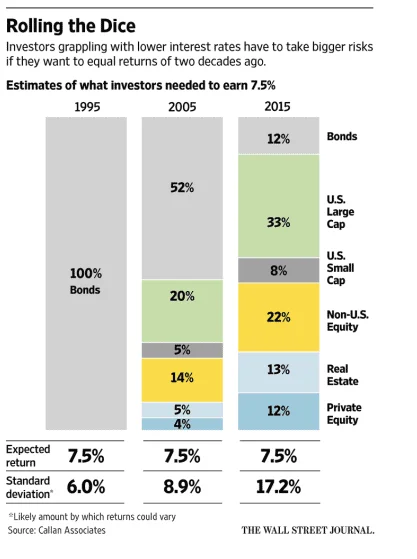
This reflexive dynamic between Fed policy and investor behavior has second-order implications as well. By forcing investors to pursue higher-yielding foreign debt (driving prices up and yields down), the Fed can essentially export its policy abroad.
There are other ramifications as well when we take into account institutional investor mandates (pension funds, insurance companies, endowments, etc.). Many instituti
Read the full report
This report is part of Delphi Pro.
- 800+ Pro reports across every major sector
- Talk directly with our analysts
- Private community of funds and builders
Already a Pro member? Log in
0 Comments